Valuation
Why 70% of collections does not tell you what a dental practice is worth
Two dental practices can collect the same amount and leave their owners with very different incomes. A useful valuation needs to explain that difference.
Download the guide PDF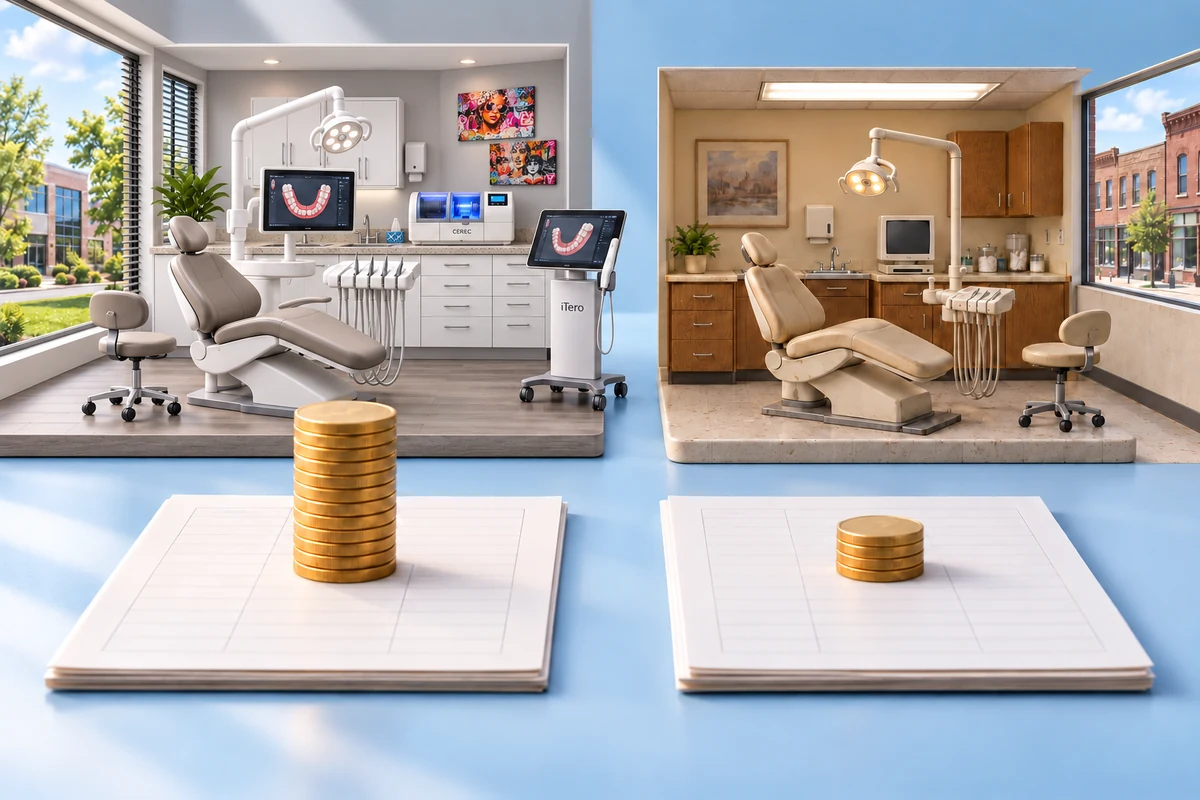
The shortcut misses the important differences
Multiplying annual collections by 70% produces a quick number. It does not establish what a particular dental practice is worth. The same percentage cannot explain different overhead, staffing needs, equipment condition, patient relationships or future investment requirements.
A revenue multiple can be a comparison point when the underlying transactions are relevant. It should not replace an analysis of the practice being bought or sold.
Same collections, different earnings
Consider two illustrative practices, each collecting $1 million annually. Practice Green has operating expenses of $500,000; Practice Blue has operating expenses of $700,000. Applying the same 70% shortcut values both at $700,000, even though the amounts left after those expenses differ by $200,000.
| Illustrative annual figures | Practice Green | Practice Blue |
|---|---|---|
| Collections | $1,000,000 | $1,000,000 |
| Operating expenses | $500,000 | $700,000 |
| Remainder before other obligations | $500,000 | $300,000 |
| Value under the 70% shortcut | $700,000 | $700,000 |
This simplified example is not an appraisal or a prediction of personal take-home pay. Owner compensation, acquisition financing, taxes, capital spending and other adjustments need consistent treatment before comparing actual opportunities.
Ask what the buyer can sustain
A buyer needs to understand what the practice can support after its ongoing costs and acquisition obligations. Two identical purchase prices can create very different financial pressures when the underlying earnings differ.
Review the actual financing terms and operating budget together, including working capital, equipment needs and the buyer's clinical role. Request a lender's current debt-service estimate and compare it with the practice's adjusted earnings before comparing opportunities.
Look at what transfers with the practice
Patient relationships, an established team and an effective hygiene program are part of the operating business a buyer is considering. The assessment also needs to address the lease, location, facilities, equipment and payer arrangements.
A procedure mix that depends heavily on the seller's specialized skills may not transfer unchanged. Conversely, services referred out today may represent opportunities for a suitably qualified buyer. Neither possibility should be treated as guaranteed future income.
Start with the records and the decision
The right scope depends on whether you are considering a sale, evaluating a partnership or planning ahead. Begin with recent financial statements and tax returns, collections and production reports, staffing information, the lease and an equipment summary.
We can discuss the assumptions behind the numbers and the information needed for your intended decision. The goal is a defensible understanding of this practice, rather than a percentage applied without context.